

MAJORITY: Mobile banking analysis by Appwee
I approached MAJORITY as a practical finance app rather than as a replacement for every banking service. Its focus is clear: helping people manage a US account and debit card, send money home, and work toward building credit without requiring an SSN. That combination makes it especially relevant to newcomers, international families, and anyone who needs a simpler entry point into everyday US money management.
In my experience, the appeal is less about having the largest possible collection of banking tools and more about reducing the barriers around getting started. The app is free, carries an Everyone age rating, and is developed by MAJORITY USA, LLC. It has reached over a million installs and holds a 4.7 average from around 23 thousand ratings, which suggests that its straightforward approach resonates with a substantial user base.
Still, I would not judge it only by its attractive starting point. A financial app has to fit the way you receive money, pay bills, transfer funds, and handle identification. The important question is not simply whether it costs anything to download, but whether its particular combination of access, transfers, debit-card use, and credit-building support matches your daily situation.
How MAJORITY fits into everyday money management
A focused account for people who need a US starting point
The central idea is a US account and debit card designed for people who may not have an SSN. That immediately separates MAJORITY from traditional banks that often make account opening feel tied to a long-established financial history. I see this as its most meaningful point of difference, because access can matter more than an impressive list of secondary features when someone is settling into a new country or supporting relatives across borders.
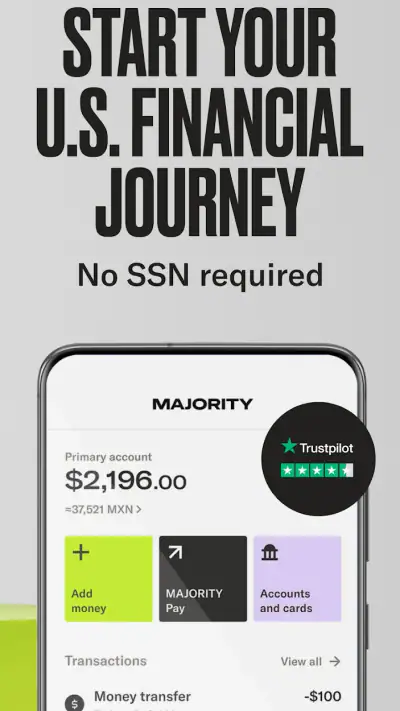
The account can serve as a place to receive and organize everyday money, while the debit card offers a familiar way to spend. That makes the app easier to understand than a collection of disconnected remittance services and prepaid tools. Instead of switching between one service for transfers, another for spending, and a separate product for credit goals, a user can begin by exploring the tools gathered around one financial profile.
That convenience should not be confused with universal compatibility. A person who already has a full-service bank, strong credit history, and sophisticated investing needs may find the app less useful as a primary financial home. MAJORITY makes more sense when access and simplicity are the priorities.
A realistic use case: getting paid and supporting family
Imagine someone who has recently moved to the US and needs a practical way to manage incoming money while sending part of it to relatives abroad. They may want a debit card for groceries and transport, a US account for routine finances, and a way to send money home without opening several unrelated accounts. In that situation, the app’s design direction feels coherent.
I would use it as a central checkpoint for that routine: receive money, keep enough available for local expenses, review the balance before sending anything, and transfer only what the household budget allows. That last step is important. Remittance convenience can make sending money feel effortless, but the app cannot replace a spending plan. I would decide the amount first, then use the transfer feature, rather than treating the available balance as money that is automatically safe to send.
For families, another useful habit is separating regular support from occasional transfers. A user could note which payments are recurring in their own budget and check each transaction inside the app instead of relying on memory. This is a small workflow, but it reduces the common mistake of sending money twice during a busy month or forgetting how much remains for local bills.
What the credit-building angle really means for users
The promise of building credit is appealing, particularly for someone who has little or no established US credit history. However, I would approach this part with patience. Opening an account or using a debit card is not the same as instantly creating a strong credit profile. Credit-building tools need to be understood on their own terms, and users should read the in-app explanations carefully before assuming that ordinary spending alone will produce the result they want.
My practical advice is to treat credit building as a long-term objective rather than the immediate reason to spend more. Use the account for transactions you already need, keep records, and avoid changing your budget simply to pursue a credit outcome. If your main goal is a mortgage, vehicle loan, or detailed credit optimization, compare MAJORITY with products designed specifically for that purpose before making it your only strategy.
The free starting point and what value means here
MAJORITY is free to download and use as an app, so the initial decision does not require paying an upfront purchase price. That makes it easy to test whether the account structure suits you. The free entry is particularly helpful for users who are still deciding how much of their financial life they want to move into a mobile service.
At the same time, “free” should be interpreted carefully in finance. A free app is not automatically a free transaction service. Transfer-related costs, card-related charges, exchange-rate differences, or other conditions can affect the real value of a financial product, and those details should be checked in the current terms and inside the transaction flow before confirming an important payment. I would never choose a remittance service based only on the download price.
The strongest value comes from consolidation. If MAJORITY lets you handle the account, card spending, family transfers, and credit-building journey in a way that feels manageable, the free access can be genuinely useful. If you only need to send money occasionally, a dedicated remittance service may be easier to compare transaction by transaction.
Where the app can save effort
The first advantage I noticed is conceptual rather than flashy: the app is built around a specific audience. Someone without an SSN does not have to begin by translating a traditional bank’s assumptions into their own situation. That can make the first steps less intimidating, especially when financial vocabulary and US account procedures are unfamiliar.
The second advantage is the relationship between local spending and international support. A debit card handles ordinary purchases, while the account can also be part of a family-support routine. This is more useful than having a remittance app that exists only at the moment of sending money, because everyday spending and cross-border obligations often affect the same balance.
The third advantage is the possibility of building a more organized financial history. Even if the credit-building component is not a complete solution, having one place to observe money coming in, spending going out, and transfers leaving the account can help users develop better habits. I would especially recommend reviewing transactions on a fixed day each week and checking whether transfers still fit the month’s essentials.
Small workflows that make the experience safer
I would begin by using the debit card for predictable purchases rather than moving every financial activity into the app immediately. This creates a low-risk trial period. After a few weeks, you can judge whether the balance information, transaction review, and transfer process fit your routine before relying on it for more important payments.
For international transfers, I would compare the final amount received, not just the amount you type into the sending screen. The useful comparison is the money that reaches the recipient after any applicable costs and currency conversion. This is one of the most important non-obvious checks because a service can look inexpensive at the start while producing a less favorable final result.
I would also keep a second payment method available during the transition. That is not a criticism unique to MAJORITY; it is sensible with any mobile financial service. A backup card or account can prevent a locked phone, delayed transfer, or account-review interruption from becoming an emergency when you need groceries, transport, or a bill payment.
Tradeoffs compared with traditional banks
Compared with a conventional bank, MAJORITY may feel more approachable for its intended audience. Traditional institutions often offer broader financial ecosystems, including more mature lending, savings, branch, and account options, but they can also be less welcoming to people who do not fit standard onboarding expectations. MAJORITY’s advantage is focus; the traditional bank’s advantage is breadth and familiarity for established customers.
A traditional bank may be the better choice if you need cash deposits, extensive account types, in-person help, business banking, or a long-term relationship that includes multiple lending products. I would also favor a conventional institution for someone who wants to keep a substantial emergency fund in a familiar banking structure and does not need the app’s specific access benefits.
Compared with a prepaid card, MAJORITY appears more ambitious because it connects card spending with an account, money transfers, and credit-building goals. A prepaid product may be simpler for controlled spending, gifting, or a limited-purpose budget. MAJORITY is more compelling when the user wants a broader financial routine rather than a card that holds a fixed spending amount.
Compared with a dedicated remittance app, the choice depends on frequency. A remittance specialist may offer a more focused comparison of destinations, delivery methods, and transfer pricing. MAJORITY can be more convenient when sending money home is only one part of the user’s weekly finances. I would compare both options for a large or urgent transfer instead of assuming that the integrated option is always the cheapest.
Limitations I would take seriously
The first limitation is that the app’s usefulness depends heavily on your personal eligibility and financial needs. The no-SSN positioning is valuable for the people it serves, but it does not mean every user will find the same onboarding experience or the same range of services. Anyone with unusual documentation, complex income, or business requirements should expect to verify that the account fits before making it central to their finances.
The second limitation is concentration risk. Keeping your spending account and transfer activity in one app is convenient, but it also means that a problem with access can affect several parts of your routine at once. I would not close every other account simply because MAJORITY is easier to start with.
The third limitation concerns expectations around credit. Users looking for an immediate score increase may be disappointed if they treat the feature as a shortcut. Credit is a gradual process, and a responsible budget matters more than chasing a promised outcome. The app can support a plan, but it cannot make an unaffordable payment affordable.
There is also a learning curve around transfers. Even when the interface is clear, international money movement involves recipient details, timing, conversion, and the possibility of costs. I would double-check the recipient before confirming and save transaction records for household budgeting. These habits are essential when the money is intended for someone else’s rent, food, or medical needs.
Who is most likely to get real value
I think MAJORITY is strongest for newcomers to the US who want a practical account without an SSN, people who regularly support family abroad, and users who prefer managing spending and transfers from a phone. It is also worth considering if you want to explore credit-building without beginning with a traditional bank relationship that feels difficult to access.
It can suit someone who values a clear, limited purpose. You do not need to be a finance enthusiast to benefit from an account that brings local spending and family transfers closer together. A user who checks balances regularly, plans transfers before sending them, and reads the cost details can get more value than someone who downloads it and treats it as an automatic financial solution.
I would suggest skipping it as your main option if you need advanced investing, business features, branch service, extensive cash handling, or a broad range of credit products. I would also look elsewhere if your only requirement is the lowest possible price for occasional international transfers. In that case, compare dedicated services for the exact country, amount, delivery method, and exchange rate you use.
Device support and the practical setup decision
The current version is 5.14.0, and the app supports operating systems from version 9 onward. That makes the technical requirement relatively approachable for users with older compatible devices, although I would still keep the operating system updated and use a phone that receives security updates. Finance apps deserve more care than ordinary entertainment downloads.
Because the content rating is Everyone, the app is positioned for a broad audience. In practice, financial responsibility still matters more than the age label. A parent or guardian helping a younger user should focus on spending limits, transfer decisions, and account security rather than assuming that an Everyone rating explains how the financial tools should be used.
During setup, I would have identification details, a reliable phone connection, and the information needed for the account process ready. I would also make sure the phone is protected with a strong screen lock and avoid signing in on a shared device. These are simple steps, but they matter more when the app is connected to a debit card and money intended for relatives.
My buy-or-skip verdict
My verdict is positive, with a clearly defined audience. MAJORITY offers free access to a mobile finance experience centered on a US account, debit-card spending, sending money home, and credit-building support. That is a useful combination for people who face barriers with conventional banking or who want their local and international money routines closer together.
I would recommend trying it if the no-SSN account access is relevant to you and you regularly need both everyday spending and family transfers. Start with modest activity, inspect the final cost of transfers, and keep a backup payment option while you learn the service. Those steps let you test the real value without making an abrupt change to your entire financial life.
I would skip it when your needs are broader than its focused purpose or when transfer price is the only thing that matters. A traditional bank can be better for a full financial relationship, while a remittance specialist can be better for a narrowly defined international payment. For the right user, though, the strongest reason to choose MAJORITY is access combined with convenience, not the word “free” by itself.
After reviewing the app as a finance tool, I see it as a practical bridge rather than a universal bank replacement. Its value comes from making a specific financial journey easier: establishing a US account, using a debit card, supporting family abroad, and taking gradual steps toward credit. If that journey describes your situation, MAJORITY is worth considering. If it does not, choosing a more specialized alternative may give you better control and clearer value.
Gallery
MAJORITY: Mobile banking Pros and Cons
- Simple mobile banking tools for checking balances and managing everyday finances.
- Convenient access to account information without visiting a bank branch.
- Useful transaction overview helps users monitor recent spending activity.
- Mobile-first design can be easier for users who prefer managing finances by phone.
- May offer helpful financial features alongside standard banking services.
- Availability and features may depend on your country
- account type
- or eligibility.
- Some users may find identity verification and onboarding time-consuming.
- Mobile banking requires a stable internet connection for most account actions.
- Support response times may vary when resolving account or payment issues.
- Users should review fees and service terms before relying on the account regularly.
MAJORITY: Mobile banking Frequently Asked Questions
What is MAJORITY: Mobile banking, and who is it designed for?
MAJORITY is a mobile banking and financial services app designed primarily for immigrants, international families, and people who need convenient ways to manage money across borders. After installing the app, users can typically access features such as a spending account, debit card services, international money transfers, bill payment options, and mobile connectivity benefits, depending on their location and current plan availability.
Is MAJORITY a real bank, and is my money protected?
MAJORITY provides banking-related services through partner financial institutions rather than operating exactly like a traditional bank in every market. Before opening an account, review the app’s current terms to understand which institution holds your funds, what protections apply, and whether deposit insurance is available. You may also need to complete identity verification and provide personal information during registration.
What documents are required to open a MAJORITY account?
The registration process generally requires users to verify their identity and provide accurate personal details. Depending on your country, immigration status, and the services you want to use, MAJORITY may request a government-issued identification document, a valid phone number, an address, and additional information required by financial regulations. Approval is not always instant, so prepare clear, valid documents.
Can I send money internationally with MAJORITY?
One of MAJORITY’s main attractions is its focus on international money transfers and financial support for families in different countries. Transfer availability, supported destinations, exchange rates, fees, delivery times, and limits can vary considerably. Before confirming a transaction, check the complete cost and recipient details in the app, since transfers may not be reversible after processing.
Does MAJORITY charge monthly fees or other service costs?
MAJORITY may use a membership or subscription-based pricing model, and some features can involve additional charges. Costs may include monthly plans, international transfer fees, card-related fees, ATM charges, exchange-rate margins, or optional services. Pricing can change by country and plan, so carefully review the fee schedule shown during signup and before using a paid feature.














